Facebook
 X
 Pinterest
 Copy Link
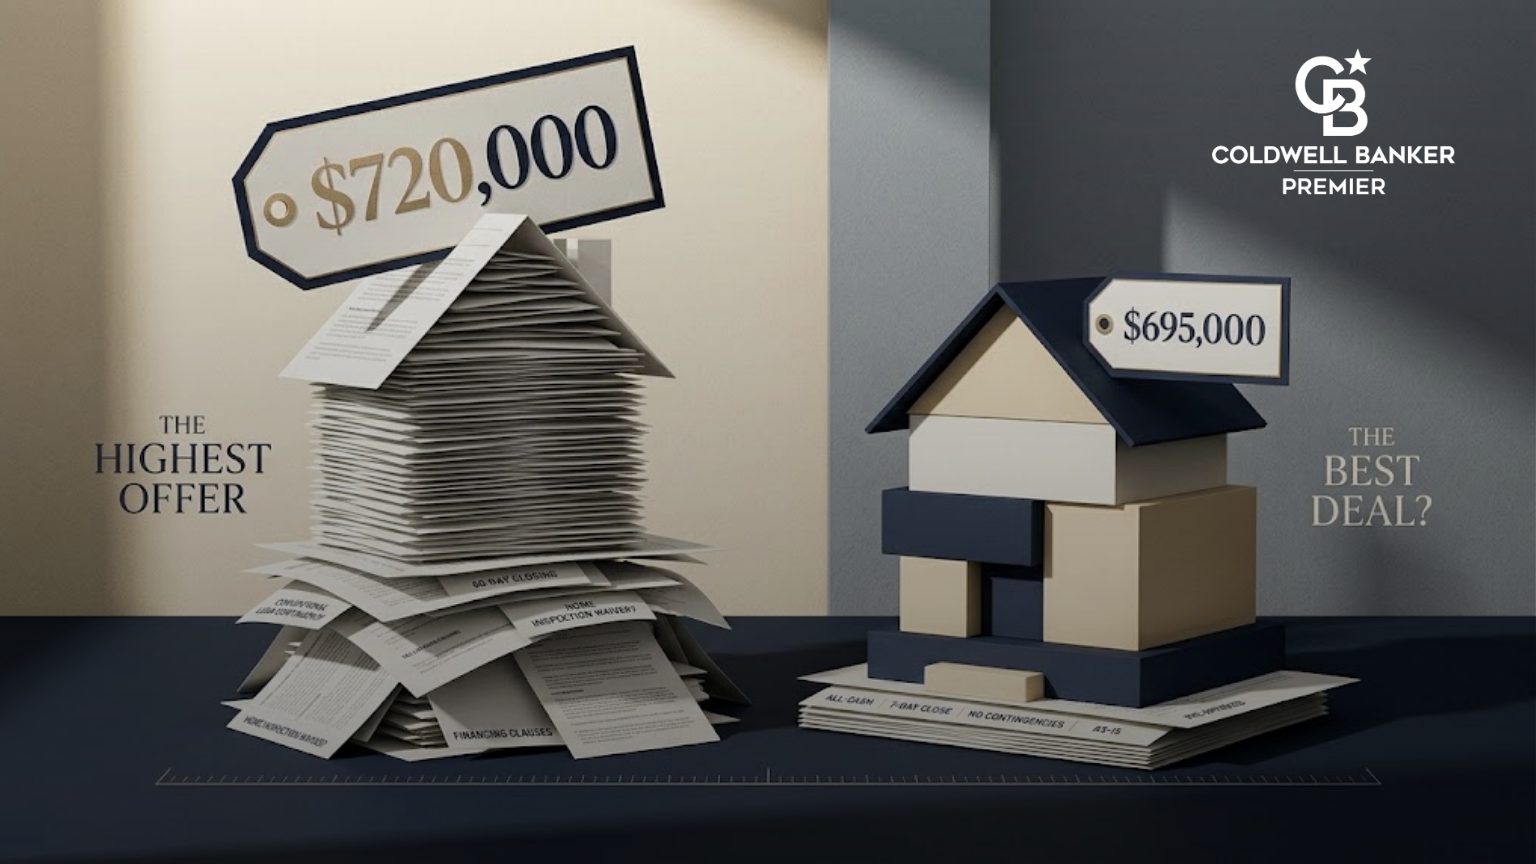
A buyer offers more than the asking price. It sounds like an easy decision, right?
Not necessarily.
The offer with the biggest number may also come with more conditions, a longer timeline, or a greater chance of complications before closing. Another offer might be lower on paper but better aligned with your goals and more likely to move forward smoothly.
If you’re selling your home, the goal isn’t simply to accept the highest price. It’s to choose the offer that makes the most sense for your situation.
Look Beyond the Offer Price
The purchase price gets attention, but it doesn’t tell the whole story. Before making a decision, review the terms that can affect your proceeds, timeline, and confidence in the transaction.
1. Financing and proof of funds
How is the buyer planning to pay? A financed offer may depend on mortgage approval, while a cash offer may have fewer financing-related steps. Neither guarantees a successful closing. Review the buyer’s documentation and discuss any concerns with your agent.
2. Inspection terms
Some buyers include an inspection contingency, allowing them to inspect the property and potentially negotiate repairs or other terms. The specific wording matters. Understand what the buyer can request and how the contingency could affect the transaction.
3. Appraisal contingency
If the home appraises below the agreed purchase price, the buyer’s financing and ability to proceed may be affected, depending on the contract and available funds. An offer with appraisal-related protections can carry different risks from one where the buyer has agreed to cover an appraisal gap.
4. Closing timeline
When do you need to move? If you have already purchased another home, need time to find your next one, or want to close quickly, the proposed settlement date can be just as important as the price.
5. Seller concessions and other costs
A buyer may ask you to contribute toward closing costs, repairs, or other expenses. Those requests can reduce the amount you ultimately receive. Compare the complete financial picture, not just the headline offer.
Compare What You Could Actually Walk Away With
Two offers at different prices can produce very different outcomes once you consider costs and terms.
For example, imagine one buyer offers $410,000 but requests $8,000 in seller concessions. Another offers $405,000 with no seller concessions.
Before accounting for other costs, the first offer would leave $402,000 after the requested concession, while the second would leave $405,000. That doesn’t automatically make the second offer better, because other terms and expenses still matter. It shows why looking at the full offer is important.
Your agent can help you compare the estimated proceeds from each offer and identify terms that could create additional uncertainty.
Consider the Risk, Not Just the Reward
Every offer comes with some uncertainty. The important question is how comfortable you are with the conditions attached to it.
A higher offer with several contingencies may require more negotiation before closing. A lower offer with terms that better fit your needs may be worth serious consideration. However, no financing type, deposit amount, or contingency structure guarantees that a buyer will close.
Ask your agent to explain the strengths, trade-offs, and potential complications in each offer. If a term is unclear, get clarification before making a decision.
Choose the Offer That Fits Your Goals
The right offer depends on what matters most to you.
Are you focused on maximizing proceeds? Do you need a particular closing date? Would you prefer fewer contingencies, or do you have flexibility if negotiations take longer?
There is no single answer that works for every seller. Your priorities, local market conditions, contract terms, and the details of each offer all matter.
A strong real estate agent helps you compare those details, understand your options, and negotiate terms that align with your goals.
Make Your Next Move With Confidence
Selling your home is a financial decision, but it is also a personal one. The best offer is the one that balances price, terms, timing, and risk in a way that works for you.
Before you sign, look at the entire offer. Ask questions, compare the likely net proceeds, and make sure you understand the obligations each contract creates.
The highest offer may get your attention. The right offer should make sense from start to finish.
Frequently Asked Questions
Should I always accept the highest offer on my home?
No. Compare the price alongside financing, contingencies, seller concessions, closing date, and other contract terms. The best choice depends on your priorities and the specific offers you receive.
Does a cash offer guarantee a faster or safer closing?
No. A cash offer may avoid some mortgage-related steps, but inspections, title issues, contract terms, and other factors can still affect the transaction.
What do seller net proceeds mean?
Net proceeds are the estimated amount you receive after accounting for the sale price and applicable costs, such as mortgage payoff, closing expenses, agreed concessions, and other transaction costs.
Can I negotiate after receiving an offer?
Often, yes. Depending on the offer and local rules, you may be able to negotiate price, contingencies, closing dates, concessions, or other terms. Your agent can explain the available options and help you respond.
The Best Offer Is About More Than Price
Selling your home is a big decision. Connect with a trusted Coldwell Banker Premier real estate professional who can help you compare offers, understand the terms, and choose the option that best fits your goals.
Connect With a Real Estate Agent Explore PremierMove
Visit PremierMove.com or call 800.835.0811 to connect with a local Coldwell Banker Premier real estate professional.
Coldwell Banker Premier
Where The Pros Work.
PremierMove.com
M. | 800.835.0811
Offices Serving VA, WV, DE, MD, NC, PA, FL, & D.C.